Showing posts with label Roofing the Villages FL. Show all posts

Thursday, February 19, 2026

Roof Types for Insurance

Your roof does more than keep the rain out. For insurance companies, it’s one of the first things they evaluate when deciding how much to charge you—and whether to cover you at all.

Insurance underwriters look at four core factors when assessing your roof: material, shape, age, and condition. Each of these elements directly influences your home insurance premiums, your coverage limits, and even your eligibility for certain policies. In many states, roof-related claims rank among the most common and expensive.
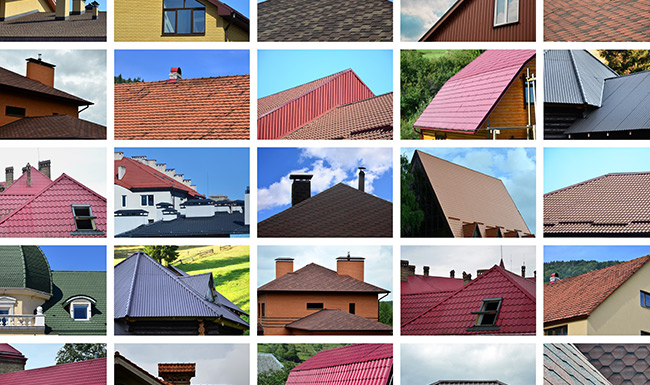
roof types for insurance

This guide walks you through the main roof shapes and roofing materials, explains how insurance companies assess each one, and shows you how to use this knowledge before a replacement or new build. The focus here is practical: how each type of roof affects your premiums, claim payouts, eligibility for coverage, and potential discounts.

What you’ll learn:

  • How insurers evaluate roofs and set premiums
  • The insurance pros and cons of common roof shapes (gable, hip, flat, gambrel, mansard)
  • How different roof materials (asphalt, metal, tile, slate, wood, synthetic) influence your rates
  • Other factors, like roof age and attachments that swing your costs
  • Practical steps to lower your premium through smarter roof choices

How Insurance Companies Evaluate Roofs

Insurers treat the roof as one of the highest-risk components of your home. It’s the first line of defense against hail damage, high winds, fire embers, and heavy rain. When any of these causes damage, the roof is usually where claims start.

Because of this exposure, homeowners’ insurance carriers put significant weight on roof characteristics during underwriting. They’re not just looking at whether your roof exists, they’re analyzing its risk profile in detail.

Key underwriting factors insurers consider:

  • Roofing material: Fire resistance, impact ratings, and expected lifespan all influence how carriers price your policy. A metal roof and an old asphalt shingle roof are evaluated very differently.
  • Roof shapes and pitch: The geometry of your roof determines how wind and water behave. Hip roofs perform differently from gable roofs in hurricane zones.
  • Roof age: Many insurers tighten coverage or increase deductibles once roofs pass 15–20 years. Some switch from replacement cost to actual cash value after certain age thresholds.
  • Local weather exposure: If you’re in a hail belt, hurricane zone, or fire-prone areas, underwriters weigh your roof’s ability to withstand harsh weather conditions more heavily.
  • Previous claim history: Homes with prior roof claims may face higher premiums or exclusions.
  • Condition documentation: Carriers often use roof inspection reports, photos, and sometimes satellite imagery to assess the current condition before binding coverage.
  • Installation quality: Subpar workmanship increases the risk of failure, which insurers factor into their pricing.

It’s also worth noting that many policies apply different coverage rules for the roof than for the rest of the structure. After your roof reaches a certain age, your policy might cover only actual cash value (depreciated) rather than full replacement cost for wind damage or hail claims.

Common Roof Shapes and Their Insurance Impact

Roof geometry affects more than curb appeal. The shape of your roof determines how wind pressure builds during storms, how effectively rain runoff drains away, and how much surface area is exposed to hail and debris.

Insurers don’t “like” or “hate” specific shapes in isolation. Instead, they price the added or reduced risk that each configuration presents. In hurricane-prone Florida, for example, a hip roof might qualify for premium discounts that a gable roof wouldn’t receive. In a low-wind inland area, the difference may be negligible.

The following subsections cover the most common roof shapes from an insurance perspective, and not a design standpoint.

Gable Roofs
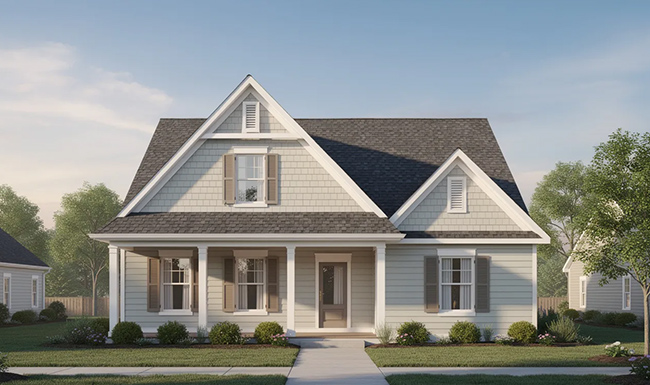
residential home featuring a traditional gable roof

Gable roofs are among the most common roof shapes in North America. If you notice two sloping sides that meet at a ridge, forming a classic triangular shape at each end of the home, this is a gable roof.

From a drainage standpoint, gable roofs perform well. A moderate-to-steep pitch sheds water and snow effectively, which helps limit water-infiltration claims over time.

However, gable roofs are particularly vulnerable in windy regions. The open gable ends can catch high winds, creating uplift that can tear off shingles, damage sheathing, or even collapse the end wall. This makes them higher-risk in hurricane and tornado zones.

Insurance considerations for gable roofs:

  • In low-wind areas, gable roofs typically receive average or moderate premiums due to their straightforward construction and good drainage
  • In coastal states like Florida and the Carolinas, gable ends may lead to higher rates or stricter underwriting requirements
  • Reinforcement measures (hurricane straps, gable-end bracing, improved sheathing attachment) can sometimes earn modest discounts or avoid surcharges
  • Wind-mitigation inspections in some states specifically assess gable-end reinforcement

Hip Roofs
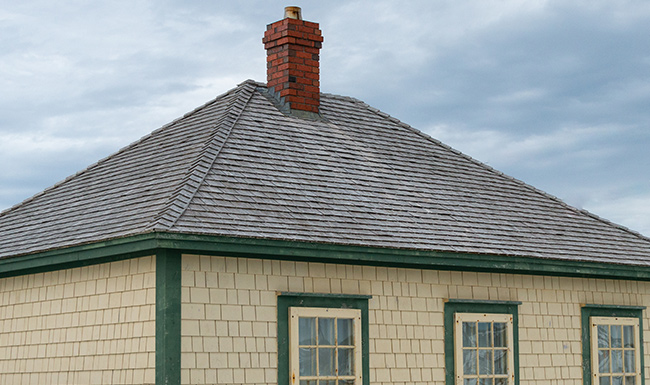
hip roof

A hip roof has slopes on all four sides that meet at a ridge or converge at a single point. This design gives hip roofs more aerodynamic stability than gables because there are no flat end walls for wind to catch.

In many coastal and high-wind states, homes with hip roofs can qualify for lower windstorm or hurricane insurance premiums. Wind-mitigation inspections often document roof shape to determine eligibility for credits.

Insurance benefits of hip roofs:

  • Studies and data suggest hip roofs offer 2-3 times the wind uplift resistance of comparable gable roofs
  • Some insurers cite double-digit percentage savings compared to gable roofs in high-wind zones
  • The construction cost is slightly higher, but long-term insurance costs can be notably lower
  • Even with a hip roof, you still need proper flashing, quality underlayment, and wind-resistant covering materials to fully capture insurance benefits

For homeowners building new or replacing a roof in hurricane-prone areas, the hip roof configuration deserves serious consideration.

Flat Roofs
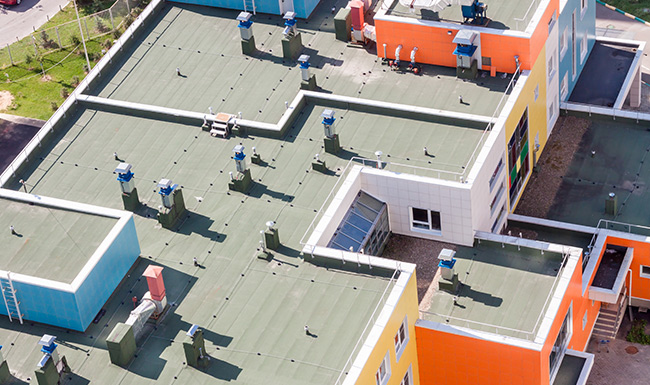
flat roof

Flat roofs are low-slope systems commonly found on commercial buildings and modern-style homes. They typically use membrane materials like TPO, EPDM, or modified bitumen rather than shingles or tiles.

The primary insurance concern with flat roofs is drainage. Without an adequate slope, water tends to pond on the surface. This ponding, combined with debris accumulation and membrane failures, significantly increases the risk of leaks and interior water damage claims.

Insurance implications for flat roofs:

  • Many insurers charge higher premiums for flat roofs due to elevated water-intrusion risk
  • Older flat roofs may face limited coverage options or stricter maintenance requirements
  • Some carriers decline to write new policies on homes with aging flat roof systems
  • Well-designed drainage (scuppers, internal drains) and documented regular maintenance can help mitigate premium increases
  • Commercial policies often factor in roof-access risks like foot traffic and HVAC equipment placement

If you have a flat roof, keeping inspection and maintenance records is especially important for avoiding claim disputes.

Gambrel and Mansard Roofs
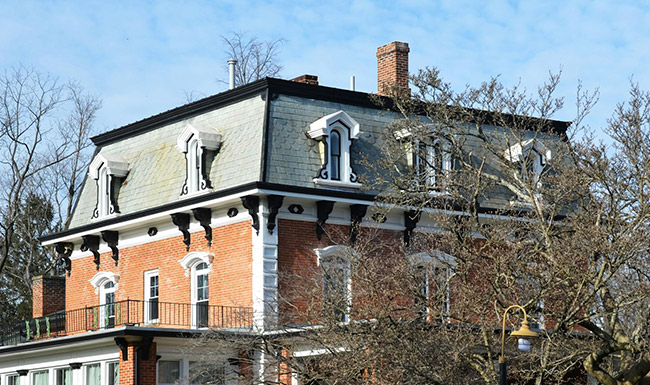
mansard roof

The gambrel roof features two slopes on each of its two sides, creating the familiar barn-style profile. The mansard roof applies the same concept to all four sides, with a steep lower slope and a shallower upper slope, often creating extra attic space.

Both designs increase the total roof surface area and create more edges and joints, increasing the potential for water entry and exposure to wind pressure and hail.

Insurance considerations:

  • Complex framing and detailing mean higher repair costs, which insurers reflect in premiums
  • More joints and transitions increase the likelihood of leaks over time
  • In heavy snow areas, the steep lower sections shed snow well, but the flatter upper sections require careful design to avoid ponding and ice dams
  • Insurers often treat gambrel and mansard roofs as moderate to higher-risk configurations
  • The aesthetic appeal of these roof styles may potentially lead to higher insurance rates

If you’re considering a gambrel roof or mansard roof for the extra attic space they provide, factor in the long-term insurance cost implications.

Other Roof Shapes (Domes, Curved, and Specialty Designs)
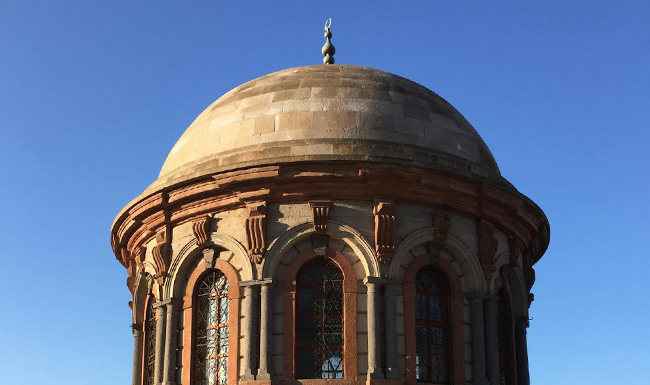
dome curved roof

Dome and curved roofs, along with highly customized architectural designs, are most often found on high-value or unique properties. While some rounded shapes perform well in wind (there are no flat surfaces to catch gusts), they come with their own insurance challenges.

Key insurance considerations:

  • Specialized construction limits the pool of contractors who can repair or replace these roofs
  • Limited contractor availability and custom materials drive up repair and replacement costs significantly
  • Insurers may place these roofs in higher-cost tiers or require higher dwelling limits
  • Owners should work with both a contractor and their insurance provider in advance to verify coverage limits and replacement-cost assumptions

If you own a home with an architecturally unique roof, getting pre-loss documentation of replacement costs can prevent unpleasant surprises after a claim.

Common Roof Materials and How Insurers View Them

Material choice is at least as important as shape when it comes to underwriting. Your roofing material affects fire resistance, hail resistance, wind performance, and life expectancy–all factors that directly influence your insurance rates.

Insurers often rely on standardized ratings as proxies for risk:

  • Fire ratings: Class A (highest), Class B, and Class C indicate resistance to fire spread
  • Impact ratings: UL 2218 testing classifies materials from Class 1 to Class 4, with Class 4 products withstanding the equivalent of 2-inch hailstones
  • Manufacturer wind warranties: Higher-rated products suggest better performance in high winds

The three main factors insurers weigh for materials:

  • Durability: How long will this roof last before needing replacement?
  • Repair cost: When damage occurs, how expensive is it to fix?
  • Total-loss risk: How likely is catastrophic damage from fire, hail, or wind?

Asphalt Shingles

Asphalt shingles are the most popular roofing material in the United States, covering approximately 80% of residential homes. Standard three-tab shingles, typically last 15–25 years, depending on climate and product quality.

From an insurance standpoint, an asphalt shingle composition roofing product is very predictable. These roofs are relatively inexpensive to replace, which helps keep claim severity moderate. Insurance companies assess them as middle-tier risk—not the best, but far from the worst.
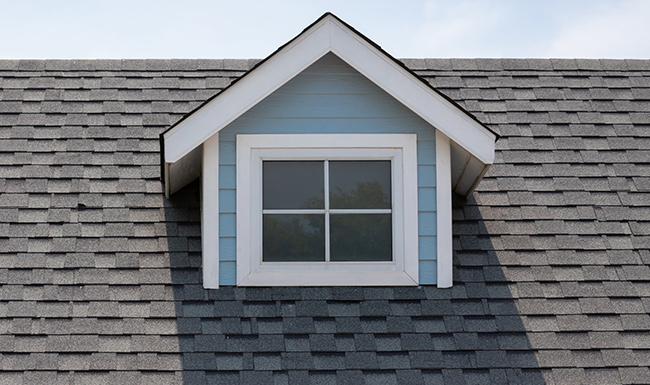
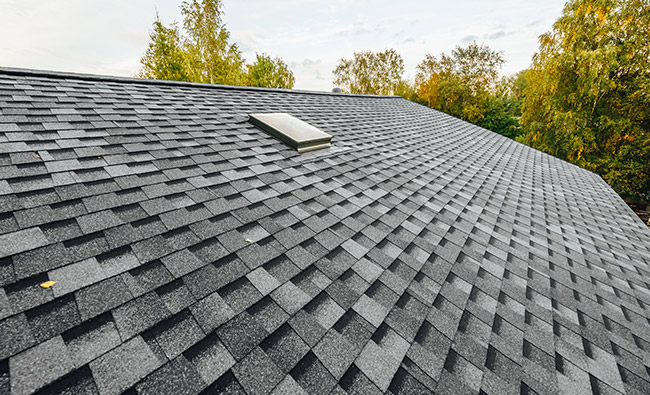
close-up asphalt shingles on a residential roof

Insurance considerations for asphalt shingles:

  • Standard three-tab shingles may perform poorly in severe hail and high winds
  • Architectural (dimensional) shingles offer improved durability
  • Class 4 impact-resistant shingles can significantly lower premiums in hail-prone states
  • Many insurers offer specific “hail-resistant roof” credits when policyholders install and document Class 4 products
  • IBHS studies suggest Class 4 materials reduce hail claims by a significant percentage

The cost-effectiveness of asphalt shingles makes them accessible, but upgrading to impact-resistant versions often pays for itself through insurance savings over time.

Metal Roofing

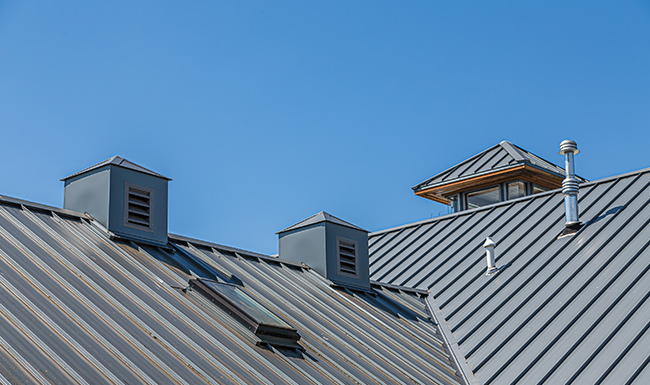
Metal roofs—including standing seam systems and metal shingles—are lightweight, durable, and long-lasting. A properly installed metal roof can last 40–70 years, far outlasting most other materials.

For insurers, metal roofs check several important boxes. Their exceptional durability and strong fire resistance make them particularly valuable in wildfire-prone states like California. In Southern states like Georgia and Alabama, metal roofs can earn premium discounts of up to 25%.
metal roof

Why insurers favor metal roofs:

  • Class A fire resistance reduces ignition risk from embers
  • High wind resistance makes them suitable for hurricane zones
  • Many products achieve Class 3 or Class 4 impact ratings
  • Snow and debris shed effectively from the smooth surface
  • Long lifespan means fewer replacement claims over time

One caveat: cosmetic denting from hail may not be covered if it doesn’t impair the roof’s function. Review your policy language carefully regarding cosmetic damage exclusions before assuming all hail damage will be covered.

While the initial installation cost exceeds that of asphalt, many insurers treat metal as a “preferred” roofing material due to lower long-term risk.

Clay and Concrete Tile Roofs

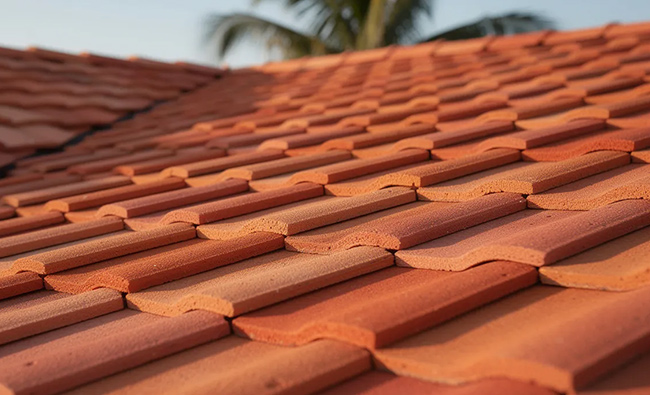
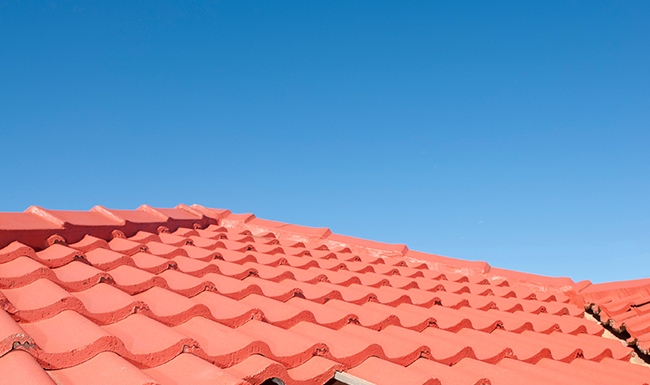
Clay tiles and concrete tiles are heavy, long-lasting materials commonly seen in warmer climates like California, Florida, and the Southwest. They offer excellent fire resistance, rot immunity, and minimal maintenance over lifespans often exceeding 50 years.
clay concrete tile roof

From an insurance perspective, tile roofs present a mixed picture.

Advantages:

  • Class A fire ratings make them favorable in fire-prone areas
  • Long lifespan reduces frequency of replacement claims
  • Strong resistance to rot and insect damage

Challenges:

  • Heavy roofing materials require structural adequacy verification
  • Wind-driven debris and hail can crack tiles
  • Skilled labor is required for repairs
  • Matching older tiles can be difficult and expensive
  • Underlayment failure can occur even when tiles look intact

Insurers may carefully scrutinize older tile roofs, requesting inspection documentation before providing or renewing coverage. Annual premiums for tile roofs typically range from $1,000 to $1,500–lower than many alternatives, but claim severity can be high when damage occurs.

Slate Roofing

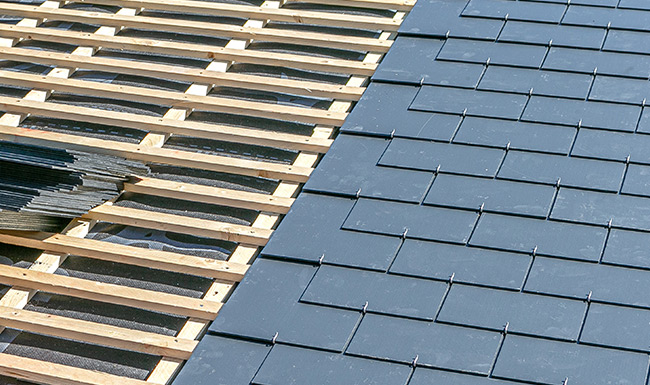
Slate roofs represent the premium tier of roofing materials. Natural stone slate can last 75–100+ years with minimal maintenance, offering unmatched longevity and Class A fire resistance.

However, slate roofs create unique underwriting challenges due to their extremely high replacement costs.
slate roof

Insurance profile for slate roofs:

  • Low fire and decay risk reduces claim frequency
  • Extremely high repair costs and specialized labor increase claim severity
  • Heavy weight may require proof of structural adequacy
  • Hail and impact damage can crack individual slabs
  • Repairs are typically done piece-by-piece, driving up claim amounts even for partial damage
  • Annual premiums can range from $1,000 to $1,500

Insurers view slate as a low-frequency but high-severity material. You’re less likely to file claims, but when you do, they tend to be expensive.

Wood Shingles and Shakes

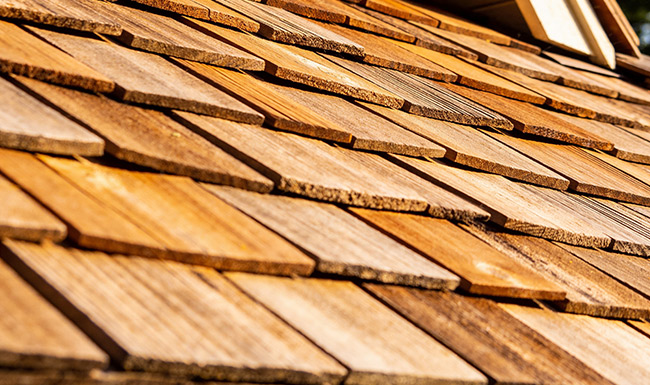
Wood roofs—including cedar shingles and shakes—offer natural aesthetic appeal and were historically common across the country. Today, they face significant insurance scrutiny.
cedar shingle shake roof

Major insurance concerns:

  • High flammability creates substantial fire risk, especially from windborne embers
  • Many insurers in fire-prone regions charge significantly higher premiums, restrict coverage, or decline new business on untreated wood roofs
  • Susceptibility to mold, mildew, and insect damage leads to more frequent maintenance and repairs
  • Timely repairs and regular treatment are essential to maintain insurability

Modern fire-retardant treatments can improve wood’s insurability, achieving Class A assembly ratings in some cases. However, not every insurer will accept treated wood as equivalent to inherently fire-resistant materials.

If you have an older, untreated wood roof, proactively contact your insurer before assuming replacement coverage will be available after a loss.

Synthetic and Composite Roofing (Including Impact-Resistant Products)

Synthetic roofing products are engineered to mimic the appearance of wood, slate, or shake while offering superior performance characteristics. Products like CeDUR shakes, for example, achieve both Class A fire ratings and Class 4 impact resistance.

Insurance benefits of synthetic roofing:

  • Many products achieve Class A fire and Class 4 impact ratings simultaneously
  • Lighter weight than natural slate or tile reduces structural concerns
  • Lower maintenance requirements than natural wood
  • Insurers in hail-prone and fire-prone states often reward these ratings with premium discounts of 10-30%

Because these are newer technologies, some carriers may have limited historical loss data. You may need to provide documentation of UL ratings and manufacturer certifications to qualify for specific discounts.

Before selecting a synthetic brand, verify with your insurance provider which ratings qualify for credits in your state.

Other Roof Factors That Change Insurance Costs

Beyond shape and material, several other factors can swing your premiums and coverage in either direction.

Roof age is a major consideration. Many insurers reduce coverage or switch to actual cash value once a roof reaches 15–20 years for asphalt roofs or 30+ years for longer-lasting materials. An old roof that’s past its expected lifespan may face non-renewal, especially in markets that have tightened after recent catastrophe losses. Conversely, a new roof often improves your standing with insurers.

Underlayment, decking, and fastening systems also matter:

  • Modern water-resistant membranes and ice-and-water shield in cold climates reduce leak risk
  • Hurricane clips and enhanced fastening in wind zones improve wind damage resilience
  • These improvements can qualify for discounts through programs like IBHS FORTIFIED Roof certification

Common attachments that increase risk:

  • Skylights (additional leak paths)
  • Solar panels (more penetrations, potential damage, complexity)
  • Rooftop HVAC units (weight, additional sealing requirements)
  • Chimneys with poor flashing
  • Satellite dishes
  • Walkable roof decks or rooftop gardens

Each attachment creates potential leak paths and claim complexity. Insurers factor these into their underwriting.

Maintenance matters too. Keeping gutters and drains clear, documenting inspections, and making timely repairs all reduce the likelihood of denied claims for neglect. Regular maintenance can also improve your standing with underwriters at renewal time, helping to achieve lower insurance costs.

Energy efficiency features like cool roof coatings and proper ventilation, while primarily aimed at reducing energy costs, can also extend roof life and reduce thermal stress—indirectly benefiting your insurance profile. Some newer solar panel installations on energy-efficient metal roofs may even qualify for additional incentives.

Which Roof Types Insurance Companies Tend to Prefer
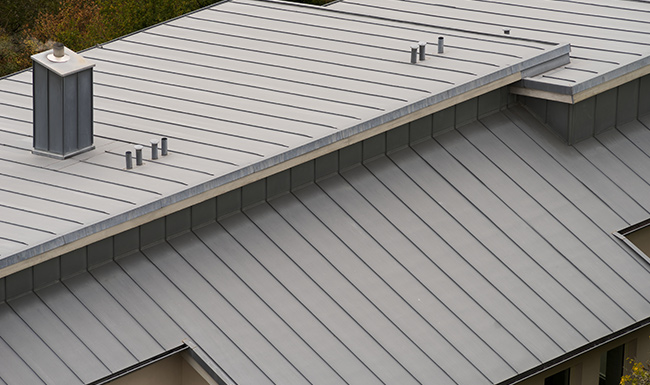
standing-seam metal roof

If you’re wondering what insurance companies favor most, here’s the synthesis:

Materials insurers typically prefer:

  • Class 4 impact-resistant asphalt shingles
  • Standing-seam metal roofs
  • Fire-rated tile and composite systems
  • Durable materials with documented certifications

Shapes insurers typically prefer:

  • Hip roofs in high-wind and hurricane zones due to superior wind resistance
  • Steeper pitches that shed water and debris effectively

Configurations that often earn the best pricing:

  • Hip roof shape combined with impact-resistant materials
  • Documented wind-mitigation features (hurricane straps, reinforced connections)
  • Roofs under 10-15 years old with good maintenance records

In wildfire zones, non-combustible materials like metal, tile, and rated synthetic products are often preferred, or even required, to maintain coverage.

It’s important to note that what an insurer “likes most” varies by company guidelines, state regulations, and current catastrophe exposure. There’s no single universal favorite—the right roof for lower premiums in Colorado’s hail belt may differ from the ideal choice in Florida’s hurricane zone.

Practical Steps to Lower Your Premium with Smarter Roof Choices

You can often influence your long-term insurance costs by planning roof replacements with risk and rating in mind—not just aesthetics and upfront price.

Before replacing your roof:

  1. Contact your agent first. Confirm what discounts exist for Class 4 impact resistance, Class A fire rating, hip roof configurations, or certified wind-mitigation features. Ask specifically how much each factor is worth in premium reduction.
  2. Understand age-based coverage changes. Ask at what age your policy switches to actual cash value for hail or wind damage. This information helps you evaluate whether a shorter-life material (cheaper upfront) or a longer-life material (better long-term value) makes more sense for your situation.
  3. Factor in the right roofing material. Compare the upfront cost difference against potential insurance savings over 20-30 years. A $5,000 premium on metal over asphalt might pay for itself through lower premiums and fewer claims.
  4. Consider the roof style impact. If you’re in a high-wind area and building new, the additional cost of a hip roof over a gable may be offset by decades of lower insurance rates.

After installation:

  • Keep all records: invoices, product data sheets with UL ratings, installation photos, and any inspection reports
  • These documents may be required to apply discounts or support future claims
  • Store copies digitally where they won’t be lost to the damage you’re trying to claim

Ongoing maintenance:

  • Schedule regular inspections, especially before and after storm seasons
  • Document any repairs with photos and receipts
  • Keep gutters, drains, and flashing in good condition

The goal is to choose the right roof that balances purchase price, expected lifespan, local weather risks, and insurance implications. For many homeowners, this means spending more upfront for durable materials and favorable shapes that deliver lower premiums and fewer costly repairs over decades.

Your next step: Before your next policy renewal or the next major storm season, review your current roof condition with both a qualified roofer and your insurance provider. Understanding how your roof affects insurance now—rather than after a loss—puts you in a much stronger position to protect both your home and your budget.

Roofing the Villages
(352) 293-2449

For the original version of this article visit: https://roofersthevillagesfl.com/roof-types-for-insurance/

Monday, January 26, 2026

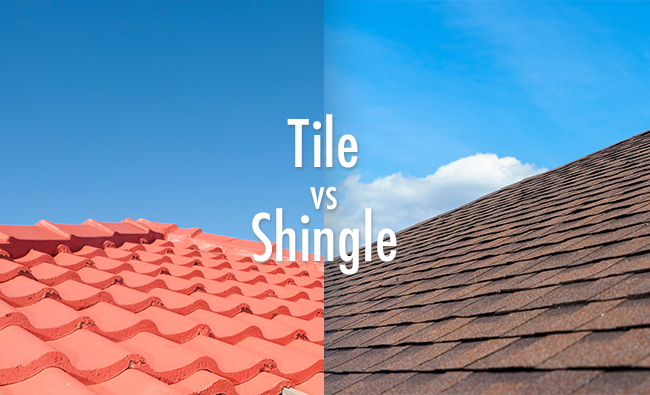
Tile Roof vs Shingle Roof in Florida

If you’re a Florida property owner weighing tile roof vs shingle roof options, here’s what you need to know upfront: asphalt shingles are typically the better short-term and budget-friendly choice, while tile roofs deliver superior long-term durability, energy efficiency, and storm resistance. Both can protect your home, but they perform very differently under Florida’s punishing sun, hurricane seasons, and heavy rainfall.

tile roof vs shingle roof in Florida

In Florida’s demanding climate, expect asphalt shingles to last roughly 15–25 years before needing replacement. Concrete and clay tiles, when properly installed, commonly deliver 30–50+ years of service, with some tile roofs exceeding that range entirely. The difference becomes even more pronounced after major storm events, where tile roofs consistently sustain less damage than their shingle counterparts.

Here’s a quick comparison for Florida property owners:

  • Upfront cost: Shingles run $3–6 per square foot installed; tile typically costs $8–15 per square foot
  • Lifespan: Shingles average 15–25 years in Florida; tile averages 30–50+ years
  • Hurricane/wind resistance: Premium shingles rated to 130–150 mph; quality tile systems can exceed 150–180 mph
  • Energy efficiency: Tile roofs can reduce cooling costs by 10–20% compared to standard shingles

Before making your decision, consider how long you plan to own the home, your available budget for upfront costs versus long-term savings, and what your insurance company requires or incentivizes in your specific wind zone.

Tile vs Shingle Roof – What’s the Difference?

Both tile and shingle roofs are common across Florida, but they’re made from entirely different materials and require distinct installation approaches. Understanding these key differences helps you make an informed choice for your property.

A shingle roof in modern Florida construction typically uses asphalt shingles reinforced with fiberglass mats and coated with ceramic granules for UV protection. Installers nail these shingles in overlapping courses across the roof deck, creating a layered barrier against water. If your Florida home was built after the 1990s, there’s a good chance it has architectural asphalt shingles. This dimensional style offers better wind ratings and a more textured appearance than older three-tab designs.

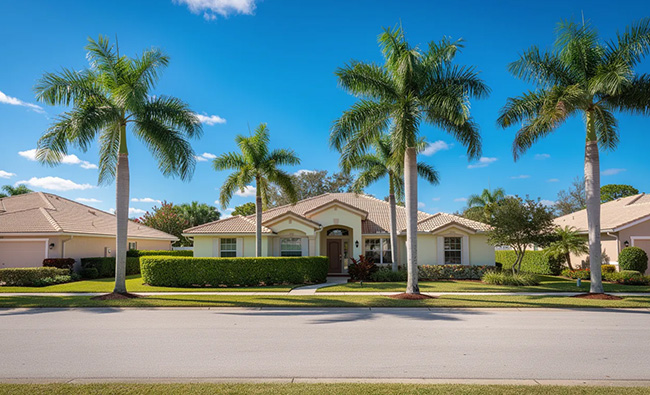
A tile roof uses clay and concrete tiles (or increasingly, synthetic composites) arranged in interlocking or overlapping patterns. These roofs are closely associated with Mediterranean, Spanish Revival, and coastal architectural styles you’ll see throughout The Villages, Miami, Naples, St. Augustine, and Tampa Bay communities. Clay tiles have been protecting Florida homes since Spanish colonial settlements in the 16th century, and concrete tiles became popular as a more affordable alternative in the mid-20th century.

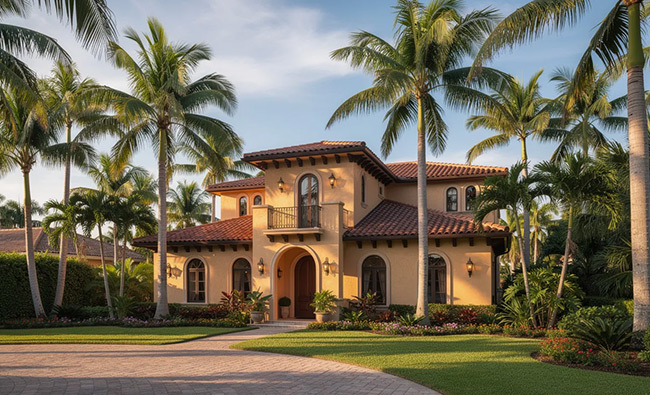
Florida home featuring a terra cotta tile roof in a Mediterranean architectural style

The most significant practical difference between tile and shingle roofs is weight. Tile is significantly heavier—concrete and clay tiles weigh 7–10 pounds per square foot compared to shingles at just 2–3 pounds per square foot. This added weight means tile roofs often require structural engineering review and potentially additional structural support, especially on older Florida homes built before current building codes.

Both roofing systems depend heavily on what’s underneath them. Proper underlayment and flashing are critical for any Florida roof, given the state’s heavy rain and wind-driven moisture during hurricane season. The roof deck preparation, waterproofing membrane, and edge detailing matter just as much as the visible roofing material itself.

Shingles offer a straightforward replacement process that works on virtually any existing structure. Tile demands more planning, potentially significant structural modifications, and specialized installation skills—but rewards that investment with decades of additional service life.

Cost: Upfront Price vs Long-Term Value in Florida

Florida labor rates and material costs fluctuate with demand, especially after major storms when roofers are in high demand. However, the cost gap between shingle and tile roofs remains consistent: tile costs roughly 2–3 times as much upfront as shingles for the same roof size.

For a typical 2,000 square foot Florida roof, here’s what you can expect to pay for materials and professional installation:

  • Asphalt shingles: $5,000–$20,000 total (architectural grade, code-compliant)
  • Concrete tile: $15,000–$30,000 total
  • Clay tile: $20,000–$30,000+ total

Several factors drive these costs beyond just the roofing material itself. Tile installations often require structural engineering review ($500–$1,500), potential truss reinforcement ($5,000–$15,000 on older homes), and more labor hours due to the complexity of cutting and fitting tiles around hips, ridges, and penetrations. Disposal fees for removing an old roof, permit costs in Florida municipalities, and the premium for hurricane-rated products all add to your final invoice.

First-time installations on new construction typically cost less than full replacements. When replacing an existing roof, you’re paying for tear-off, disposal, possible deck repairs, and upgrades to underlayment that meet current Florida Building Code standards—standards that have tightened significantly since Hurricane Andrew in 1992.

The long-term cost picture flips the upfront equation. Over 40 years of home ownership, a shingle roof will likely need two or three complete replacements at $8,000–$20,000 each, plus ongoing maintenance costs for algae treatment and storm repairs. A tile roof installed today may only need underlayment replacement (not the tiles themselves) during that same period. When you run the numbers, tile often costs 40–60% less over a 40-year ownership period despite the higher upfront cost.

For many homeowners, the question isn’t “which is cheapest today” but rather “which is cheapest over the next 30-40 years.” If you’re planning to stay in your Florida home long-term, tile often emerges as the more cost-effective roofing solution, despite its higher installation cost.

Maintenance and Repairs in Florida’s Climate

Florida’s combination of intense UV exposure, coastal salt air, heavy rain, and tropical storm systems creates maintenance demands that differ from those in other states. Both tile and shingle roofs require attention, but the nature and frequency of that maintenance vary significantly.

Shingle roof maintenance in Florida typically includes annual inspections to check for granule loss, curling edges, and lifted shingles—especially after storm events. The state’s humidity encourages the growth of algae (specifically Gloeocapsa magma), which creates the distinctive black streaks you see on older roofs. Treating this algae with zinc strips or professional cleaning costs $200–$500 and may be needed every few years. Sealant around flashings, vents, and roof penetrations requires regular inspection and periodic reapplication.

shingle roof maintenance

Tile roof maintenance focuses on different concerns. You’ll want periodic inspections every 3–5 years to identify cracked or displaced tiles, check for debris accumulation in valleys, and assess the condition of the underlayment. Individual tiles can crack from impacts—fallen branches or even careless foot traffic—but replacements are straightforward if matching tiles are available. The tiles themselves require minimal maintenance beyond keeping debris cleared.

Here’s an important distinction: while tile roofs need fewer day-to-day repairs, when damage does occur, the cost tends to be higher. A skilled tile roofer may charge $500+ for a service call, and matching replacement tiles for older or custom profiles can be difficult or expensive to source. Shingle repairs are generally simpler and cheaper per incident, but you’ll likely have more incidents over the roof’s lifetime.

Both roof types benefit from annual inspections plus immediate checks after any major storm. Florida insurers increasingly require documented roof condition for policy renewals, making regular inspections a practical necessity rather than just good maintenance practice.

Durability and Lifespan in Florida Conditions

Published lifespan estimates for roofing material often assume moderate climates—not Florida’s relentless sun, salt air, and hurricane exposure. Realistic life expectancy in Florida conditions runs shorter for shingles and can vary significantly based on installation quality and location.

For shingle roofs in Florida, expect these realistic lifespans:

  • Basic 3-tab shingles: 10–15 years (rarely installed on new construction)
  • Architectural/dimensional shingles: 15–25 years
  • Premium laminated shingles: 20–30 years under ideal conditions

For tile roofs in Florida:

  • Concrete tiles: 30–50+ years for the tiles themselves
  • Clay tiles: 50–75+ years (some century-old clay roofs still function in Key West)
  • Underlayment beneath tiles: Often needs replacement at 20–30 years

Shingles in Florida experience accelerated aging due to intense UV radiation, which breaks down the asphalt binders and causes granule loss. High winds during tropical storms and hurricanes create uplift forces that peel back or tear shingles entirely. Repeated cycles of wind-driven rain can work moisture under shingle edges, leading to deck damage and leaks. Post-Hurricane Ian assessments in Southwest Florida found 40–60% shingle loss on many homes in 130 mph wind zones.

Tile roofs age differently. The tiles themselves—whether concrete or clay—are remarkably durable against UV, heat, and moisture. What fails first is typically the underlayment, fasteners, or flashings beneath the tiles. A tile roof might look perfect from the street, while the waterproofing membrane beneath has reached the end of its life. Quality installation with premium underlayment rated for Florida conditions significantly extends this timeline.

Coastal properties face additional challenges from salt spray, which accelerates corrosion of metal fasteners and flashings on both roof types. Homes with heavy tree cover may see more debris impacts and shaded areas that encourage moss and algae growth. An inland Florida home with good sun exposure typically gets the longest service from either roofing material.

Climate Performance: Heat, Humidity, and Florida’s Weather

Florida’s climate presents specific challenges that affect how tile and shingle roofs perform day to day: year-round high humidity, intense solar gain from spring through fall, frequent afternoon thunderstorms, and hurricane seasons running from June through November.

Asphalt shingles absorb significant heat from Florida’s sun. Dark-colored shingles—common on older Florida homes—can reach surface temperatures exceeding 150°F on summer afternoons, radiating that heat into the attic space below. This heat absorption directly increases air conditioning loads and energy costs. Even lighter-colored shingles don’t offer much relief, since the roofing material itself has limited thermal mass and ventilation.

Tile roofs handle Florida heat more effectively through multiple mechanisms. The tiles themselves have thermal mass, absorbing daytime heat and releasing it slowly rather than transferring it immediately to the attic. More importantly, the air gap created between the tile surface and the roof deck allows ventilation that carries heat away. Light-colored concrete tiles or traditional terra cotta clay tiles reflect more solar radiation than dark shingles. Studies show that tile roofs can keep attic temperatures 20–30°F cooler than shingle roofs, potentially cutting cooling costs by as much as 20%—a meaningful difference when summer electric bills in Florida regularly exceed $200–$300.

Both roof types can handle Florida’s heavy rain when properly installed with correct slope, underlayment, and flashing details. Tile systems excel at quickly shedding large volumes of water, which matters during the intense downpours common in Florida’s wet season. The key factor for either material is quality installation rather than inherent material superiority.

One advantage Florida homeowners enjoy: freeze-thaw cycles that damage tile roofs in northern states are essentially non-existent here. Concrete and clay tiles that might crack from repeated freezing in Ohio or Pennsylvania perform without that concern in Florida’s subtropical climate.

Installation Process and Structural Considerations

roof installation process in Florida

Florida’s building codes—significantly strengthened after hurricanes like Andrew (1992), Charley (2004), Irma (2017), and Ian (2022)—heavily influence how roofs must be installed. What passed inspection decades ago wouldn’t come close to meeting current requirements, especially in high-velocity hurricane zones along the coast.

Shingle installation in Florida follows a defined process. Contractors prepare the roof deck, install peel-and-stick or synthetic underlayment rated for high wind zones, and attach shingles using corrosion-resistant nails in specific patterns mandated by local code. Coastal areas and windborne debris regions require enhanced fastening schedules and may mandate specific shingle products with documented wind ratings. A competent crew can complete a typical 2,000-square-foot shingle roof in 1–2 days under normal conditions.

Tile installation is more complex and time-intensive. Before any tiles go up, the structure needs an engineering review to confirm it can handle the added weight of tile at 7–10 pounds per square foot. Installers typically use battens (horizontal strips) or direct-deck attachment methods, with mechanical fasteners or foam adhesive systems rated for high-wind performance. Cutting and fitting tiles around hips, ridges, vents, and other penetrations requires skilled labor. Expect 3–7 days for a comparable tile roof installation.

Swapping from shingles to tile on an existing Florida home triggers additional requirements. You’ll likely need structural evaluation by a licensed engineer, possible truss reinforcement or additional support, and updated engineering documentation to satisfy the current Florida Building Code. These steps add $5,000–$15,000 or more to the project cost—and several weeks to the timeline between permitting and final inspection.

The installation process for tile demands experienced, properly licensed Florida contractors who understand both the structural and code requirements. Improper tile installation—insufficient fastening, poor underlayment choices, or inadequate structural support—can lead to catastrophic failures during high winds.

Return on Investment and Florida Home Value

Both new shingles and tile roofs improve resale value compared to leaving an aging or damaged roof in place. However, the magnitude of that improvement differs substantially in many Florida markets.

Tile roofs command premium curb appeal across Florida’s coastal communities and higher-end neighborhoods. The aesthetic appeal of Spanish tile, barrel tile, or flat concrete tile profiles signals quality and permanence to buyers familiar with Florida real estate. Sales data indicates tile-roofed homes in markets like Miami can sell for $20,000–$50,000 more than comparable shingle-roofed properties. In Cost vs. Value analysis, tile roofs boosting home values by ~5–10% in Florida markets.

Shingle roofs still add resale value when replacing an old or damaged roof—buyers and appraisers recognize a new roof as a significant improvement. However, shingles may not deliver the same “premium materials” perception or long-term buyer confidence that tile provides in certain neighborhoods. In communities where tile predominates, a shingle roof might even be viewed as a downgrade.

Florida real estate transactions increasingly focus on roof age and material. Buyers worry about inheriting insurance problems, and many ask for roof credits or repairs before closing. A newer tile roof can be a strong selling point that differentiates your property, while an aging shingle roof approaching replacement age often becomes a negotiation liability.

Exact ROI percentages vary by Florida metro area. High-end coastal markets in Naples, Miami Beach, and Palm Beach see stronger tile premiums. More suburban markets in The Villages, Orlando, Jacksonville, and inland areas may show smaller differentials. In all cases, a well-maintained roof in good condition—regardless of material—outperforms a neglected one.

Shingle Roofing for Florida Homes

shingle roof property

Asphalt shingles, often called composition roofing, remain the most common roofing material across Florida subdivisions, and for good reason: they offer the lowest barrier to entry for homeowners who need a new roof without stretching their budget. Understanding when shingles make sense—and when they don’t—helps you make the right choice.

Modern shingle roofs in Florida primarily use two types: three-tab shingles (flat, uniform appearance) and architectural/dimensional shingles (layered, textured look). Architectural shingles now dominate new installations because they offer better wind ratings, longer warranties, and improved aesthetics compared to basic three-tab products. Premium laminated shingles push performance even higher, with some products warranting wind resistance up to 130–150 mph.

The advantages for Florida homeowners are practical: lower upfront cost means you can afford a code-compliant roof without financing or depleting savings. Materials and qualified installers are widely available across the state. Installation moves quickly, minimizing your home’s exposure during Florida’s rainy season. When storms do cause damage, repairs are relatively simple and affordable, and there are Class 4 impact resistant shingles that better withstand hail and severe weather.

The drawbacks are equally real: shingles simply don’t last as long under Florida’s intense sun, and they’re more vulnerable to wind damage during hurricanes. Higher heat absorption means higher cooling costs compared to reflective tile systems. Over 40+ years of home ownership, you’ll likely face multiple replacement cycles.

Shingles make the most sense in Florida when you have a limited budget and need a roof now, when you’re planning to sell the property within 10–15 years, or when your home’s structure can’t support the added weight of tile without expensive reinforcement. They’re a practical choice—just not always the optimal long-term investment for a Florida property.

Pros of Shingle Roofs in Florida

  • Lowest upfront cost per square foot makes shingles accessible for budget-conscious projects, typically running $6,000–$12,000 for a complete installation on an average Florida home.
  • Adequate wind performance for code-compliant installations in many Florida wind zones, with premium products rated to 130–150 mph.
  • Quick installation timelines of 1–2 days minimize your roof’s exposure during Florida’s unpredictable weather and rainy season.
  • Simple, affordable repairs after localized storm damage—individual shingles can be replaced for $150–$500 per repair.
  • Wide selection of colors and styles that can satisfy HOA requirements and match various architectural styles common in Florida subdivisions.
  • Readily available materials even after major storm events, when demand spikes, thanks to nationwide distribution networks and local inventory.
  • Works on virtually any structure without requiring engineering review or reinforcement for added weight.

Cons of Shingle Roofs in Florida

  • Shorter lifespan in Florida conditions compared to tile—expect 15–25 years rather than the 30-year warranties that apply in milder climates.
  • Greater vulnerability to wind uplift and missing shingles during tropical storms and hurricanes, with higher rates of insurance claims for wind damage.
  • Higher cooling costs compared to tile roofs that reflect more heat and provide better ventilation, potentially adding $300–$500 annually to energy costs.
  • More frequent replacements over long-term ownership—two or three full replacements during a 40–50 year period, versus potentially one for tile.
  • Faster cosmetic degradation under intense UV exposure, with visible fading, granule loss, and algae staining appearing within 7–10 years.
  • Petroleum-based materials contribute to landfill waste at replacement, with Florida generating millions of tons of shingle waste annually.
  • Insurance complications in some high-risk zones where carriers prefer or require more durable materials for coverage eligibility.

Tile Roofing for Florida Homes

Tile roofs dominate Florida’s coastal communities, upscale developments, and Mediterranean-inspired neighborhoods for reasons beyond mere aesthetics. These roofs deliver superior durability and weather resistance that justify their higher price in a state where extreme weather conditions are annual certainties rather than rare events.

The main tile materials you’ll encounter in Florida include concrete tiles (the most common and affordable), clay tiles (with a traditional terra cotta appearance and slightly more expensive), and specialty options such as slate tiles or composite shingles made from recycled polymers. Concrete and clay tiles both handle Florida’s heat, humidity, and salt air effectively, with clay offering a slight edge in longevity and concrete providing better affordability.

Florida Building Code requires tile roofs to meet specific wind ratings, and properly installed systems routinely achieve ratings of 150 mph or higher—sufficient for Category 4 hurricane conditions. The key phrase is “properly installed.” Tile roofs depend heavily on correct underlayment, fastening methods, and structural support to deliver their rated performance.

The performance advantages in Florida are substantial: exceptional longevity under harsh weather conditions, strong UV resistance that doesn’t degrade like asphalt, excellent performance in heavy rain, and measurably lower cooling costs. The thermal mass of tile keeps your house cooler during summer months, reducing AC runtime and energy costs.

The primary challenges are equally real: upfront costs are 2–3 times higher than for shingles, the added weight demands structural verification and possible reinforcement, and repairs require skilled contractors who may charge premium rates. Older tile roofs may have underlayment approaching end-of-life even when the tiles themselves remain sound, creating a hidden maintenance obligation.

Living with a tile roof day to day means minimal maintenance between inspections, confidence during storm season, and the aesthetic appeal that comes with durable materials designed to last for generations.

close-up concrete roof tiles in a terracotta color, used on Florida homes

Pros of Tile Roofs in Florida

  • Exceptional longevity in hot climates—concrete tiles commonly last 30–50 years, clay tiles 50–75+ years, with many homeowners never needing a full replacement during their ownership.
  • Superior wind and storm resistance when installed to current Florida codes, with systems routinely rated for 150+ mph winds and Class 4 impact ratings.
  • Measurably cooler attic temperatures thanks to thermal mass and air gap ventilation, reducing AC loads and cutting energy costs by 10–20% compared to shingles.
  • Premium curb appeal is favored in Florida’s coastal and upscale communities, with an upscale appearance that commands higher resale value and faster sales.
  • Potential insurance benefits, including discounts of 20–35% from carriers that recognize tile’s durability under Florida’s My Safe Florida Home and similar wind mitigation programs.
  • Non-combustible materials provide a Class A fire rating and superior fire resistance compared to wood shingles or composite shingles.
  • Environmentally friendly end-of-life options—concrete and clay tiles are 95% recyclable and don’t contribute to landfill waste like petroleum-based shingles.
  • Less maintenance is required between inspections, with tiles that resist algae, UV degradation, and the cosmetic deterioration common with asphalt.

Cons of Tile Roofs in Florida

  • Significantly higher initial cost at $15,000–$30,000 for a typical Florida home versus $5,000–$20,000 for shingles—the higher price represents a substantial upfront investment.
  • Added structural load requires engineering evaluation and often reinforcement on older Florida homes, adding $5,000–$15,000+ to project costs.
  • Individual tiles can crack from impacts (fallen branches, hail, careless foot traffic), requiring skilled repair that may cost $500+ per service call.
  • Underlayment replacement needs that arise before tiles reach end-of-life, typically at 20–30 years, add long-term maintenance complexity that is often overlooked at initial purchase.
  • Longer installation timelines of 3–7 days versus 1–2 for shingles, creating more exposure to weather delays and scheduling challenges.
  • Dependence on experienced contractors who are properly licensed and familiar with Florida Building Code requirements for tile, as opposed to less qualified installers, creates serious risks.
  • Matching tile challenges for repairs on older roofs where the original tile profile or color may no longer be manufactured.

Key Factors to Consider When Choosing a Florida Property

The right roofing material for your Florida home depends on your specific situation—there’s no universal “best” choice. Walking through these factors helps clarify which direction makes sense for your property.

Budget and financing: Can you afford tile’s higher upfront cost, or would financing be required? If paying cash for a roof, compare the total cost of one tile roof versus two or three shingle replacements over your expected ownership period. The cheapest option today isn’t always the cheapest option over time.

Location and exposure: Coastal properties face salt spray that accelerates corrosion. Inland homes with heavy tree cover experience more debris impacts and shaded areas that encourage growth. Direct sun exposure affects both materials, but impacts shingles more severely. Consider what your specific property faces.

Wind zone and hurricane risk: Florida’s wind zones vary significantly, and your local code requirements reflect historical storm impacts in your county. High-velocity hurricane zones along the coast essentially mandate premium materials and installation methods. Check what your building department and insurance company require.

Ownership timeline: If you’re planning to sell within 5–10 years, recouping tile’s premium may be difficult. If you’re staying 20+ years, tile’s long lifespan and lower lifecycle costs become more attractive. Be realistic about your plans.

HOA and neighborhood standards: Some Florida communities require tile roofing in their covenants. Others are predominantly shingle, where tile might look out of place. Check restrictions before committing to either direction.

Energy efficiency goals: If high summer AC bills are a concern, tile’s ability to keep your home cooler offers real savings. Homes with older or undersized HVAC systems benefit more from a reflective, ventilated tile roof.

Florida permitting and contractors: Any roof replacement requires permits and inspections. Work with licensed, insured contractors who understand the Florida Building Code and your local regulations. Get multiple bids and verify credentials before signing contracts.

Tile vs Shingle Roof in Florida: Which Is Right for You?

houses with tile and shingle roofs in a sunny Florida residential neighborhood

Choosing between tile and shingle roofs in Florida ultimately comes down to balancing upfront cost against long-term value, convenience against durability, and budget realities against performance advantages.

Shingles represent the practical, affordable choice that works for many homeowners. They meet code requirements, install quickly, and provide reliable protection at a price point accessible to most budgets. For homeowners who need a roof now, plan to move within 10–15 years, or own homes where structural limitations make tile impractical, shingles remain a sensible decision.

Tile represents the premium long-term investment—more expensive initially but delivering decades of service, lower energy costs, stronger storm resistance, and higher resale value. For homeowners staying in their Florida property long-term, living in hurricane-prone areas, prioritizing energy efficiency, or owning homes in communities where tile is standard, the additional upfront cost often pays dividends.

Here’s a simple decision framework:

  • If you plan to own your home 20+ years and can invest more upfront, tile typically delivers better long term value through fewer replacements, lower energy bills, and insurance savings.
  • If budget is your primary constraint and you need a code-compliant roof now, quality architectural shingles provide solid protection at accessible prices.
  • If your home’s structure can’t support tile weight without expensive reinforcement, shingles remain your practical option.
  • If you’re in a high-wind zone and insurance costs are significant, tile’s durability ratings may offset its higher price through premium savings.

Either roof can perform well when properly installed and maintained according to Florida’s codes and climate demands. The critical factor isn’t always which material you choose—it’s choosing a qualified Florida roofing contractor who installs it correctly.

Schedule a professional roof inspection to evaluate your current structure, confirm your local wind zone requirements, and get accurate estimates for both options. That conversation—with someone who can physically assess your property—provides the specific guidance that general comparisons can’t deliver.

To learn more about which type of tile roof is the best for you, read Best Roofing Shingles for Florida.

FAQ: Tile Roof vs Shingle Roof in Florida

Florida homeowners face unique questions about roofing materials, insurance requirements, and storm preparedness. These answers address the concerns we hear most frequently.

Will a tile roof lower my homeowners’ insurance in Florida?

Many Florida insurers offer discounts of 20–35% for tile roofs with documented wind mitigation features. Your actual savings depend on your carrier, policy type, and the specific wind rating of your roof system. Request a wind mitigation inspection after installation to maximize available credits—some homeowners save $1,000+ annually.

Can I switch from shingles to tile on my existing Florida home?

Yes, but it’s not simply a material swap. Tile weighs significantly more than shingles, so you’ll need a structural engineering evaluation and potentially truss reinforcement or additional support. Budget $5,000–$15,000+ beyond the roof itself for these modifications on older homes. Newer construction built to current codes may require minimal changes.

How do hurricanes affect shingle vs tile roofs?

Post-storm assessments consistently show that tile roofs sustain less damage than shingle roofs under equivalent wind conditions. After Hurricane Ian in 2022, many Southwest Florida shingle roofs experienced significant shingle loss in the 130 mph gusts, while properly installed tile roofs showed minimal damage. However, both systems can fail if the installation was substandard or the storm exceeds the rated capacity.

Do I need to replace my roof just to keep my insurance in Florida?

Possibly. Many Florida insurers now require roofs younger than 15–25 years for coverage eligibility, and some require inspections to verify condition. If your roof fails inspection or exceeds age thresholds, you may face non-renewal or must replace the roof to maintain coverage. Check with your current carrier and shop alternatives before making decisions.

What roof color is best for keeping my Florida home cooler?

Lighter colors reflect more solar radiation and reduce heat absorption. White or light tan concrete tiles perform best for cooling efficiency. If you prefer darker aesthetics, tile still outperforms shingles of the same color due to its thermal mass and air gap ventilation. “Cool roof” rated shingles with reflective granules offer modest improvement over standard products.

How often should I have my roof inspected in Florida’s climate?

At a minimum, schedule professional inspections annually, plus immediately after any named tropical storm or hurricane. Florida’s combination of UV exposure, heavy rain, and wind events creates wear that’s easy to miss from ground level. Document every inspection for insurance purposes—carriers increasingly require regular inspections for coverage maintenance.

Are synthetic tiles a good option in Florida?

Synthetic tiles from manufacturers like Brava offer 40–50% weight savings versus concrete or clay, often eliminating structural reinforcement needs. They carry wind ratings up to 160 mph and resist cracking better than natural materials. However, they’re relatively new products without the 50+ year track records of traditional tile. They represent a promising middle ground worth discussing with your contractor.

What happens if individual tiles crack on my roof?

Cracked tiles should be replaced promptly to prevent water intrusion. If you have matching replacement tiles (kept from the original installation), repairs are straightforward. If tiles must be sourced externally, matching older profiles or discontinued colors can be challenging and expensive. Ask your installer about keeping spare tiles for future repairs.

For answers specific to your city, roof age, and insurance requirements, connect with a licensed Florida roofing contractor who can evaluate your property in person. Every home is different, and local expertise makes the difference between general guidance and actionable recommendations.

Roofing the Villages
(352) 293-2449

For the original version of this article visit: https://roofersthevillagesfl.com/tile-roof-vs-shingle-roof-in-florida/

Thursday, April 24, 2025

Your Roof Maintenance Checklist

Need a roof maintenance checklist? The roof maintenance tips paired with this guide cover all the essential tasks, from inspections to cleaning gutters, to help you maintain a durable and safe roof that reaches its full life expectancy.

roof maintenance checklist

Key Takeaways

  • Regular roof inspections and maintenance are essential to prevent costly repairs and extend the roof’s lifespan, including checking flashing and drainage systems.
  • Cleaning gutters, trimming nearby trees, and removing moss and algae are critical tasks that help maintain effective water drainage and protect roofing materials from damage.
  • Engaging professional roofing contractors ensures compliance with building codes, provides expert inspections, and helps maintain the overall health and longevity of your roof.

Schedule Regular Roof Inspections

Routine inspections are essential for effective roof maintenance. Conducting them twice a year can significantly extend your roof’s lifespan by identifying minor issues early. Look for cracks, tears, and blisters, which, if ignored, can cause severe structural damage.

Engage professional roofing contractors for these inspections. Their trained eyes can spot issues that might be missed during a casual visual inspection. Professional inspections help identify potential leaks, damaged shingles, and other structural issues early, saving you from costly repairs in the future.

Address minor flaws promptly to prevent further damage. Staying proactive with inspections maintains the integrity of your roofing system and keeps your house safe.

Clean Gutters and Downspouts

clean gutters and downspouts on a roof

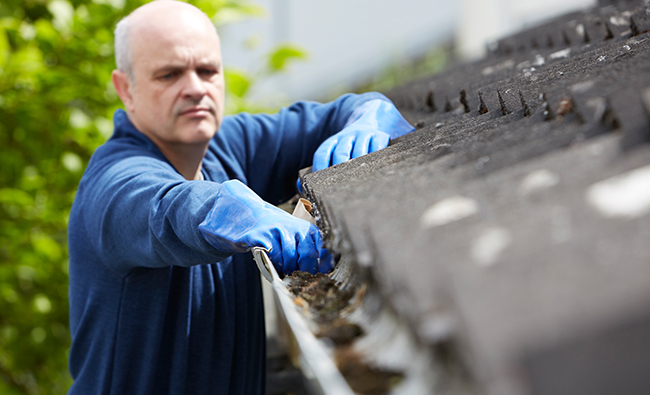
Clean gutters and downspouts are crucial for proper water drainage. Clogged gutters can’t function effectively, leading to water infiltration and potential damage. Regular cleaning prevents moisture buildup, which can lead to moss growth and shingle degradation.

Gutters should be cleared regularly by removing leaves, twigs, and other debris. Ensure downspouts are securely attached and free of blockages to prevent water pooling. Installing kick-out flashing can further enhance gutter functionality by directing water flow effectively.

Neglecting this task can lead to severe issues, such as water damage to your home’s siding and foundation, and structural damage to the roof. Ensure your gutters are working correctly by regularly cleaning them.

Trim Nearby Trees

While nearby trees add beauty, their tree branches can become a menace if left unchecked. Overhanging branches can drop debris that traps moisture on the roof. Regularly trim these branches to prevent damage to the roof shingles.

Falling limbs can cause severe structural damage. Trimming branches that shade the roof can reduce moss growth by improving sunlight exposure, maintaining both the roof’s aesthetic appeal and longevity.

Schedule tree pruning and trimming sessions regularly, especially in the spring when trees are actively growing. Use the right tools, like a ladder and pruning shears, to safely remove overhanging branches and keep your roof clear of debris and potential hazards.

Inspect and Repair Flashing

inspecting flashing on a roof

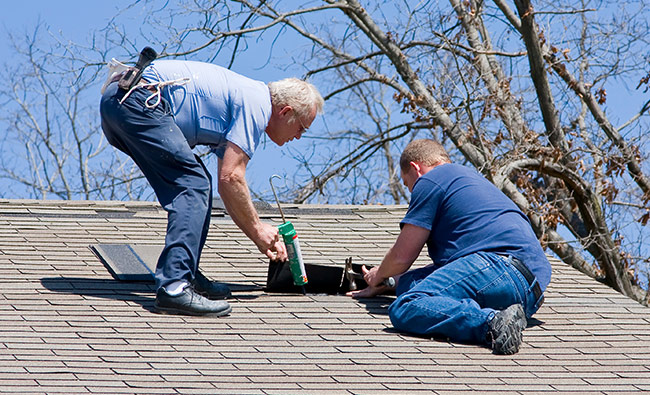
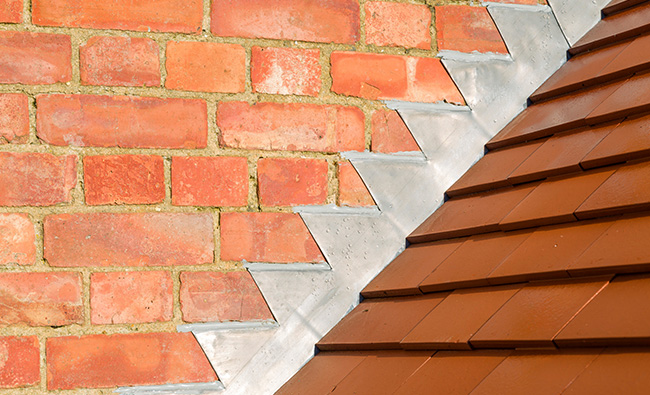
Flashing maintains a watertight seal where roof planes intersect, such as around chimneys, vents, and skylights. Regularly inspecting and repairing flashings prevents water leaks and ensures the integrity of your roofing system. Look for rust, gaps, or deterioration during inspections.

After storms, inspect the flashing for any damage. Use the right sealants to maintain the watertight seal and check caulking for cracks. Ensuring roof penetrations are sealed properly prevents leaks and extends the life of your roof.

Maintaining flashing can save you from costly repairs and help maintain your roof’s overall health. Make flashing inspection a regular part of your roof maintenance routine.

Remove Moss and Algae

Moss and algae may give your roof a rustic charm, but are harmful. Moss growing on shingles retains moisture, leading to deterioration and reduced roof lifespan. Moss growth can also obstruct proper drainage, resulting in potential water damage and leaks.

To combat moss, remove any organic matter and debris buildup on the roof. Use a gentle, eco-friendly dish soap and horticultural oil solution to remove moss safely. Consider installing zinc or copper strips to inhibit moss and algae growth for long-term prevention.

Keeping your roof free of moss and algae enhances its appearance, ensures proper water drainage, and extends its lifespan. Regular maintenance and proactive measures are key to a healthy, moss-free roof.

Check Attic Ventilation

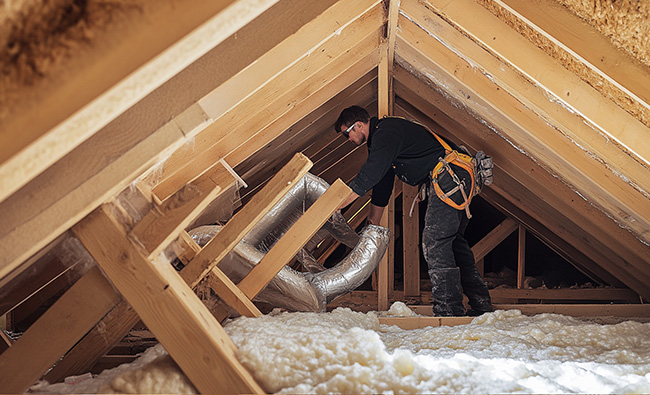
Proper attic ventilation is crucial for maintaining a healthy roof and preventing mold, mildew, and ice dams. Adequate ventilation pathways allow humid air to escape, replacing it with cool, dry air, which helps mitigate the risks of mold and mildew by preventing moisture buildup.

Check that vents are unobstructed and functioning correctly. Installing rafter vents can improve attic airflow, ensuring insulation and stored items do not block ventilation. Address any ventilation problems promptly to prevent moisture buildup from improperly vented appliances.

examine attic of a roof for damage

Proper attic ventilation supports overall roof health and energy efficiency, making it a critical component of roof maintenance.

Examine Roof Surface for Damage

Regularly examine your roof surface for signs of damage to detect issues early and prevent costly repairs. Look for blistering, cracking, tears, holes, abrasions, and loose or damaged pieces. Different types of roofs require different focus areas, such as checking tile and shingle roofs for loose or missing pieces and inspecting metal roofs for corrosion and damaged panels.

Use binoculars to inspect hard-to-reach vulnerable areas from the ground, or physically assess the roofing membrane for punctures and tears. Perform inspections after severe weather or high winds to catch any damage early. Address identified damage promptly to avoid costly repairs.

Staying vigilant and conducting regular inspections maintains the integrity of your roof and prevents minor potential issues from becoming major problems. Use a checklist to ensure nothing is overlooked during these roofing maintenance inspections.

Assess Drainage Systems

Effective drainage systems prevent water damage to your roof and home. Blocked drainage systems can lead to costly repairs. During heavy rainfall, unmaintained gutters can cause water to overflow, potentially damaging siding and foundation.

Regular inspections should include checking all roof drainage components for blockages. Verify that downspouts are securely attached and free of debris to ensure proper water drainage. Address damaged or improperly installed scuppers promptly to maintain effective water drainage.

Maintaining clean and effective drainage systems prevents water infiltration and protects your roof from potential leak damage.

Document Maintenance and Repairs

Keeping detailed records of all roof maintenance and repairs is crucial for future inspections and budget planning. A maintenance log helps track the history of roof work, allowing homeowners to plan for upcoming maintenance and budget appropriately. Note down any observed issues during inspections to ensure they are addressed promptly.

A systematic approach to documenting a maintenance checklist improves communication between homeowners and roofing contractors. This documentation helps identify recurring issues and plan preventative measures to avoid costly repairs.

Maintaining detailed records ensures your roof remains in top condition and extends its lifespan.

Engage Professional Roofing Contractors

engage professional roofing contractors for roof maintenance

Hiring professional roofing contractors is essential for maintaining your roof’s health and longevity. Professional companies adhere to ethical standards, ensuring accountability. They apply precise techniques and use high-quality materials for a durable installation.

Local roofing contractors are knowledgeable about building codes and regulations, ensuring compliance. Engaging a professional roofer is crucial for addressing significant commercial roof damage that requires specialized tools and expertise. Engaging professional contractors ensures periodic inspections and maintenance of your commercial roofs.

Investing in professional roofing services provides access to extensive knowledge and tailored solutions for roof equipment issues, ultimately saving you money by preventing costly repairs.

Roof Maintenance Summary

Maintaining your roof requires a proactive approach and a comprehensive maintenance checklist. Regular inspections, cleaning gutters, trimming nearby trees, and engaging professional roofing contractors are essential steps to ensure your roof’s longevity and performance. Addressing issues promptly and documenting all maintenance and repairs are critical for effective roof management.

By following this checklist, you can protect your investment, prevent costly repairs, and ensure your roof remains in top-notch condition. Take action today and implement these roof maintenance practices to enjoy a safe, secure, and long-lasting roof.

Roof Maintenance Inspector Frequently Asked Questions

How often should I inspect my roof?

You should inspect your roof at least twice a year, ideally in the spring and fall, to ensure it remains in good condition. Regular inspections can help identify issues before they become major problems.

Why is it important to clean gutters regularly?

Regularly cleaning gutters is essential to prevent moisture buildup that can cause moss growth and potentially lead to water infiltration and structural damage. Keeping gutters clear safeguards the integrity of your home.

What are the benefits of hiring professional roofing contractors?

Hiring professional roofing contractors ensures high-quality workmanship, compliance with building codes, and access to warranty coverage, which ultimately guarantees a durable and reliable roof.

How can I prevent moss and algae growth on my roof?

To prevent moss and algae growth on your roof, regularly remove any debris, apply eco-friendly treatment solutions, and consider installing zinc or copper strips. These measures will help protect your roof’s integrity and appearance.

Why is proper attic ventilation important?

Proper attic ventilation is essential for preventing mold, mildew, and ice dams, as it allows humid air to escape, thus promoting roof health and enhancing energy efficiency. Prioritizing adequate ventilation can significantly extend the lifespan of your roof and improve your home’s comfort.

Roofing the Villages
(352) 293-2449

For the original version of this article visit: https://roofersthevillagesfl.com/your-roof-maintenance-checklist/

Wednesday, February 26, 2025

Top 7 Common Roof Repairs

Facing problems and need your roof repaired? This article covers the most common roof repairs, like leaks, broken shingles, etc. Find out how to spot these issues and tackle repairs to keep your roof in good shape.

common roof repairs

Key Takeaways

  • Address roof leaks promptly to prevent structural damage and perform regular maintenance to extend the roof’s lifespan.
  • Detect and replace damaged shingles immediately to maintain roof integrity and avoid further issues, especially in storm-prone areas.
  • Regular gutter maintenance and proper ventilation are essential in preventing water accumulation and moisture-related problems, which can compromise roofing materials.

Roof Leaks and How to Address Them

Roof leaks rank as one of the most prevalent issues for homeowners. They are a significant concern when it comes to roofing problems. A variety of factors can cause these issues. Examples include damaged flashing, missing shingles, and clogged gutters. Addressing roof leaks promptly is crucial to prevent further damage and preserve the structural integrity of your home.

Signs of a roof leak can often be identified through water stains on ceilings and walls or the presence of mold around the house. If you notice these signs, it’s crucial to locate the source of the leak. Start by inspecting common problem areas, such as around chimneys, skylights, and vents. Minor roof repairs can often be handled by resealing these areas or replacing damaged shingles.

For more severe roof repairs, such as significant water damage or structural issues, it’s best to call in a professional roofing contractor. Emergency roof repairs may be necessary if the leak poses an immediate threat to your home’s safety. Regular roof inspections and maintenance can help prevent leaks from occurring in the first place, ensuring your roof repair remains in good condition.

Preventing costly repairs is easier than you might think. Regular roof maintenance can significantly extend the life of your roof, such as cleaning gutters and checking for potential problem areas. Prompt attention to minor repairs helps avoid more severe issues and keeps your home safe and dry.

1. Damaged Shingles

damaged shingles on a roof that needs replacement

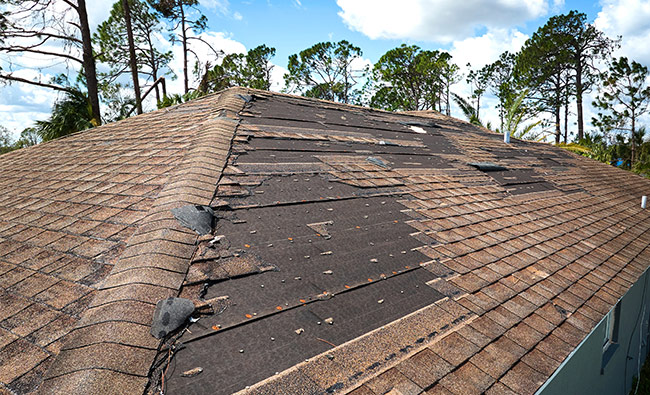
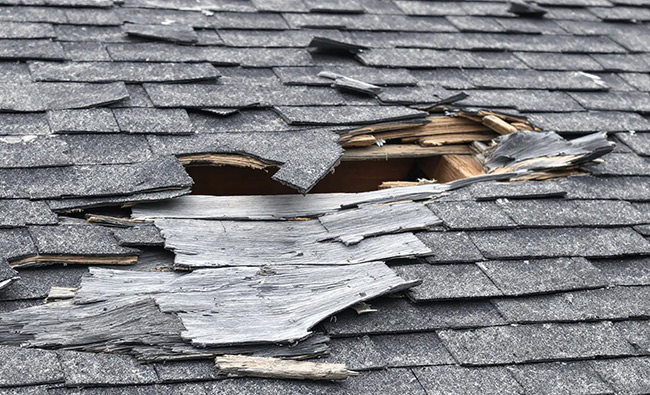
Damaged shingles are another common roofing issue that can lead to significant problems if not addressed. Routine roof inspections can help detect issues like cracked, warped, or missing shingles. Visible signs of shingle damage include dark stains, which could indicate the presence of moss or algae.

Shingles can be damaged by high winds, fallen trees, flying debris, or animals. Promptly replacing broken shingles maintains the roof’s integrity and prevents more extensive damage. If you live in a storm-prone area, replacing roof shingles immediately after a storm is critical to avoid further issues.

While replacing damaged shingles, you might face challenges such as finding an exact color match due to sun bleaching. A local roofing contractor can assist with replacing damaged shingles and ensuring a proper match. Prompt shingle repairs prevent structural damage and extend your roof’s lifespan.

2. Damaged Flashing

repairing damaged roof flashing

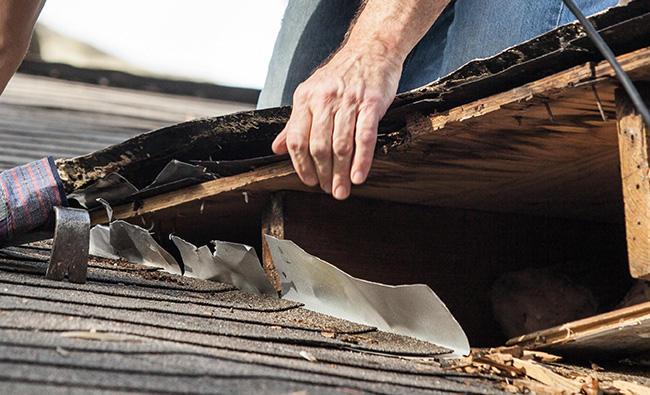
Flashing directs water away from critical areas on the roof, such as chimneys, vents, and skylights. Damaged flashing can lead to roof leaks and structural issues if not addressed promptly. Common signs of flashing damage include cracked seals, visible gaps, corrosion, water stains, and mold.

Repairing damaged flashing often involves resealing or replacing it to restore functionality. Improper installation can cause flashing to fail, leading to water flowing underneath the roofing materials and causing further damage. Regularly checking and fixing flashing issues is essential to ensure the roof’s integrity.

Noticing damaged flashing should prompt a call to a professional roofing contractor for assessment and repair. Timely repairs can prevent further damage and keep your roof in good condition. Maintaining your flashing helps avoid costly repairs and extends your roof’s lifespan.

3. Gutter Maintenance and Repair

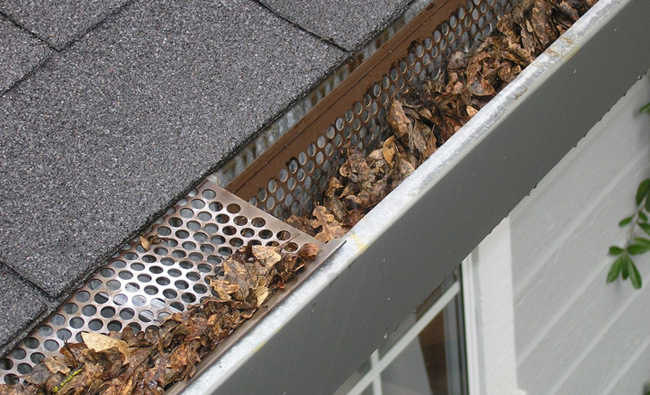
Gutters play a vital role in your home’s roofing system by directing rainwater away from the house. They eliminate water accumulation from the roofline, directing it away from the home. Clogged gutters can worsen roof problems by leading to water overflow and potential damage to fascia boards, walls, and foundations.

Common problems that arise from clogged gutters include leaks, rot, and structural damage. Regular cleaning of gutters is necessary to prevent water backup that can damage shingles and other roofing materials. Gutters should be cleaned at least twice yearly, ideally in spring and fall, to prevent issues caused by accumulated debris.

clogged gutters on a house, leads to roof damage

If your gutters overflow despite being clean, inspect for possible gutter damage and improper slope. Regular maintenance and timely repairs are essential to avoid expensive problems and ensure that your gutters are functioning efficiently.. Maintaining your roof drainage system and gutters protects your roof and home from water damage.

4. Poor Ventilation Issues

Poor ventilation can lead to significant issues like moisture accumulation, which affects the integrity of roofing materials and overall roof health. Effects of poor attic ventilation include excessive heat buildup, which can cause roofing materials to age prematurely and increase energy costs.

Proper airflow in the attic improves ventilation. This helps reduce the risk of moisture accumulation and prevents mold growth.

If issues related to ventilation are identified, it is vital to hire a licensed contractor to investigate and implement necessary repairs for effective airflow. Maintaining a healthy roof and preventing costly repairs requires proper ventilation.

5. Ponding Water on Flat Roofs

Standing water on flat roofs, commonly called ponding water, can be caused by various factors, including inadequate drainage and structural issues. Ponding water should not remain on flat roofs for more than 48 hours to prevent damage to the roof structure and materials.

Clogged drains are a common cause of ponding water on flat roofs, leading to potential leaks and damage if not addressed. Installing additional drains can alleviate pooling water issues, especially near parapet walls. Silicone-based roof coatings are effective for areas experiencing ponding water when applied correctly.

In some cases, re-pitching or overlaying the roof with a new membrane might be necessary to address ponding issues and aged roofing material. If other repair methods are ineffective, a complete roof replacement might be required. Promptly addressing ponding water prevents significant damage and extends the life of your flat roof repairs.

6. Emergency Roof Repairs

tree damage for emergency roof repairs assessed by a roofing contractor

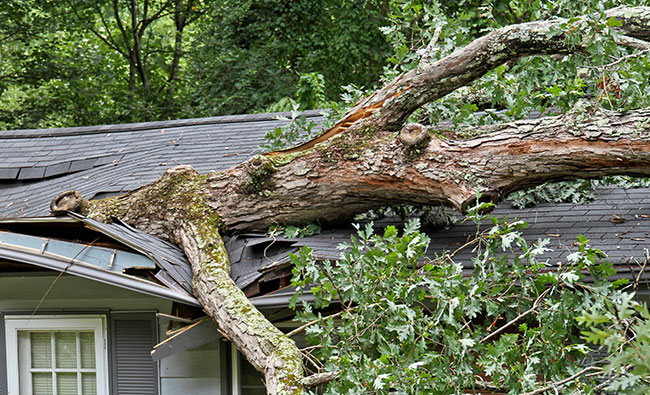
When water, fire, wind, or tree damage occurs, emergency roof repairs are necessary. Signs of an emergency include visible water leaks, large puddles on the roof, or major structural threats. Swift action and informed decisions are crucial during a roofing emergency to minimize damage.

During a roofing emergency, the first step is to contact a local roofing contractor. They will be able to assist you with the situation. Temporary tarping can be used to minimize damage until a professional can perform repairs. Documenting damage and taking photos can facilitate a smoother insurance claims process.

Immediate attention to ice dams on a roof is necessary to avoid water damage. Prompt emergency repairs prevent further damage and ensure your home’s safety. Always be prepared and know when to seek professional help to handle roofing emergencies effectively.

7. Preventive Maintenance Repairs

Regular inspections of the roof are essential. They help identify issues such as missing granules, cracks, and leaks. Scheduling at least one roof inspection per year can help identify potential problems early. Proper gutter maintenance, such as ensuring downspouts are connected, can prevent water from pooling on the roof.

Trimming trees and branches that are near the entire roof can prevent damage caused by falling limbs or abrasion. Preventive measures like timely repairs and maintenance can significantly prolong roof life and prevent costly repairs.

Proactive steps help maintain a healthy roof and avoid unexpected issues.

Choosing the Right Roofing Contractor

Choosing the right roofing contractor ensures quality work and protects your investment. Homeowners should check roofing contractors’ credentials to confirm a valid license and insurance. References from previous clients can offer insights into a contractor’s reliability and quality of work.

roofing contractor fixing damaged roof for homeowner

Obtaining multiple written estimates from roofing contractors allows for comparison of prices and services offered. Comparing quotes helps ensure competitive pricing and service evaluation for roof projects. Understanding the difference between a contractor’s workmanship warranty and the manufacturer’s warranty is crucial for long-term satisfaction.

Contractors that offer financing options may indicate financial stability and professionalism. A trustworthy contractor should provide a clear plan for their work and explain how the roofing system functions. Choosing the right contractor ensures your roofing project is completed to the highest standard.

Roof Repairs Summary

In conclusion, maintaining your roof is essential for the safety and longevity of your home. From fixing roof leaks and damaged shingles to handling poor ventilation and emergency repairs, addressing these issues with urgency can prevent costly repairs and prolong the life of your roof.

Regular inspections, preventive maintenance, and choosing the right roofing contractor are key to ensuring your roof remains in good condition. By taking proactive steps, you can protect your home and enjoy peace of mind knowing your roof is well-maintained.

Common Roof Repairs Frequently Asked Questions

What are the most common causes of roof leaks?

The most common causes of roof leaks are damaged flashing, missing shingles, and clogged gutters. Regular inspections and maintenance can help prevent these issues.

How can I identify damaged shingles?

To identify damaged shingles, look for visible signs such as dark stains, cracks, warping, or missing shingles. Addressing these issues as soon as you notice them can help prevent further damage to your roof.

What should I do if I notice damaged flashing?

If you notice damaged flashing, promptly call a professional roofing contractor for assessment and repair to prevent further damage. Taking this action can help safeguard your property from potential leaks and structural issues.

How often should gutters be cleaned?

Gutters should be cleaned at least twice a year, ideally in spring and fall, to prevent issues from debris buildup. Regular maintenance will help ensure proper drainage and avoid costly repairs.

Why is poor ventilation a problem for roofs?

Poor ventilation is a significant problem for roofs because it causes moisture buildup and excess heat, which can lead to premature aging of roofing materials. Ensuring proper ventilation is crucial for maintaining the integrity and lifespan of your roof.

Roofing the Villages
(352) 293-2449

For the original version of this article visit: https://roofersthevillagesfl.com/top-7-common-roof-repairs/

Roof Types for Insurance

Your roof does more than keep the rain out. For insurance companies, it’s one of the first things they evaluate when deciding how much to ch...